Yes. Can I cancel my health insurance during open enrollment? For a plan you buy yourself, you can cancel any day of the year, and open enrollment is the safest time to do it because you can pick a replacement in the same window. Employer plans are different: open enrollment is usually the only time you can drop them without a life event.
The real risk is not the cancelling. It is the gap. End one plan before the next one starts and every bill in between is yours.
This guide covers the rules for each kind of plan, the end date to choose, and the mistakes that leave Texans uninsured in January.
Before you cancel anything, do these three things:
- Confirm the start date of your new coverage, in writing.
- Set your old plan to end the day before that date.
- Keep the confirmation of both, in case a claim lands in the overlap.
Can I Cancel My Health Insurance During Open Enrollment?
Yes, and for most people it is the best time of year to do it. The answer depends on who sells your plan.
| Type of plan | Can you cancel during open enrollment? | Can you cancel at other times? |
| Plan you buy yourself on HealthCare.gov | Yes | Yes, any day |
| Private plan bought directly from a carrier | Yes | Yes, any day, by contacting the carrier |
| Employer plan paid with pre-tax payroll | Yes, during your employer’s window | Usually only after a life event |
| COBRA | Yes | Yes, any day |
| Medicare | Different rules and dates | Different rules and dates |
So when people ask “can I cancel my health insurance during open enrollment”, the honest answer is that the window matters less for leaving a plan than for joining the next one. Open enrollment is when the door to a new plan is open.
People search “can you cancel health insurance at any time” about 1,900 times a month in the US, according to our DataForSEO research. Most of them are really asking a second question: if I cancel, can I get back in?
Can You Cancel Health Insurance at Any Time?
For a plan you buy yourself, yes. You can end coverage on any day, for any reason, and there is no fee to cancel.
What you cannot do is buy a new marketplace plan whenever you like. Outside open enrollment you need a qualifying life event, such as moving, marrying or losing other coverage.
Here is the catch most pages leave out. Dropping a plan on purpose does not count as losing coverage. Federal rules exclude a voluntary termination, and a plan ended for unpaid premiums, from the loss-of-coverage event, as state appeal decisions applying 45 CFR 155.420(e) show.
In plain terms: cancel in March with nothing lined up and you may be uninsured until next January. That is why “can I cancel my health insurance during open enrollment” is a better question than “can I cancel today”.
Do I Have to Wait Until Open Enrollment to Cancel Insurance?
Not for a plan you buy yourself. You only need to wait if you also want a new plan and have no life event to open a special window.
Employer plans are the exception. Premiums taken from your pay before tax lock in your choice for the plan year. Your employer can only let you drop coverage mid-year after a qualifying change, such as marriage, a new baby, or gaining other coverage.
That is why open enrollment at work is the natural exit.
If you are asking “can I cancel my health insurance during open enrollment at my job”, the answer is yes, and it is often your only chance that year. Your choice for next year takes effect on the first day of the new plan year, which is usually January 1.
If you are leaving a job plan for one you buy yourself, read our guide to health insurance between jobs in Texas first. Losing job coverage can open a 60 day window. Choosing to drop it during open enrollment works differently, because you are using the open enrollment window itself.
How Do You Cancel Marketplace Health Insurance?
Log in to your HealthCare.gov account, open your application, and choose the option to end all coverage. You can also call the Marketplace Call Center at 1-800-318-2596.
You pick the end date. According to CMS guidance on terminating a Marketplace plan, coverage can end as soon as the day you act, or on a future date if you are ending it for everyone on the application.
Two details catch people out:
- The Marketplace does not match your new start date for you. You must set the end date yourself.
- Removing one person ends their coverage almost at once. If you are dropping only some people on the application, CMS suggests calling for a specific date.
If you had premium tax credits, keep the Form 1095-A you receive next year. You will need it to settle those credits on your tax return.
Can I Cancel My Health Insurance During Open Enrollment If I Am Switching Plans?
Usually you do not need to. If you are moving from one HealthCare.gov plan to another, choosing a new plan during open enrollment replaces the old one for the new year.
You can also change your mind more than once. KFF confirms you can switch to a different plan at any time while the window is open.
Timing still matters. Pick by December 15 and the new plan starts January 1. Pick between December 16 and January 15 and it starts February 1, so January stays on the old plan.
You do need to cancel yourself in these cases:
- You are leaving HealthCare.gov for a private plan bought directly from a carrier.
- You are joining a new employer plan or a spouse’s plan.
- You are moving to Medicare.
In each one, the Marketplace has no way of knowing about your new coverage. Leave the old plan running and you can be billed for both.
Which End Date Should You Pick?
The day before your new coverage starts. Nothing else protects you as well.
| Your new coverage starts | Set your old plan to end |
| January 1 | December 31 |
| February 1 | January 31 |
| The first day of a new job plan | The day before that date |
| Medicare on May 1 | April 30, as CMS shows in its Medicare transition guide |
Can I cancel my health insurance during open enrollment and pick a date in the future? Yes, for everyone on a HealthCare.gov application. Wait for the new plan’s confirmation before you submit the cancellation. A plan you selected is not a plan you have until the carrier confirms it and you pay the first bill.
What About Cancelling a Private Plan Bought From a Carrier?
Call the carrier or the agent who sold it, and ask for the cancellation in writing. Some carriers take it online, some need a signed form.
Private plans, including PPO and association plans, are not tied to HealthCare.gov. They usually end at the close of a paid month. Ask three questions before you send the request:
- What exact date will my coverage end?
- Will any premium I paid in advance be refunded?
- Will I get written confirmation of the end date?
These plans also work on their own calendar for buying. Many can be bought at any time of year, which is useful if you cancel and later need cover. Our page on association health plans explains how they work.
Is There a Penalty for Cancelling Health Insurance?
Can I cancel my health insurance during open enrollment without a fee? Yes. There is no fee to cancel, and there is no federal or Texas penalty for being uninsured. The IRS reduced the federal penalty to zero starting with tax year 2019.
The cost is the exposure. One emergency room visit or hospital stay during a gap is billed to you in full.
There are smaller costs too. A new plan starts a new deductible, so money you put toward this year’s deductible does not carry over. Cancel in October and switch in January and that is fine. Cancel in June and buy again in July and you start from zero.
Should You Just Stop Paying Instead?
No. Letting a plan lapse for non-payment is the worst way to leave it. If you are asking “can I cancel my health insurance during open enrollment by just not paying”, the clean cancellation is always better.
If you get premium tax credits, you have a 3 month grace period. In the second and third months the insurer can hold claims, and if you never catch up you can owe for the first month and lose the coverage back to that point. Without tax credits the grace period is usually shorter.
A plan ended for non-payment also does not give you a special enrollment window. A clean cancellation with a chosen end date is simpler and leaves no surprise bills.
When Should You Not Cancel?
Some reasons sound good and are not. Think twice in these cases:
- You have already met this year’s deductible. Staying through December can be worth more than the premium you save.
- You are mid-treatment. A pregnancy, surgery or ongoing care is the wrong time to change networks.
- The new plan is not confirmed. Never cancel on the strength of a quote.
- You plan to “go without for a few months”. You may not be able to get back in until next year.
- You are on COBRA and in the middle of the year. Dropping it is a voluntary end, not a loss of coverage. Compare it with COBRA alternatives in Texas first.
If you are still weighing it, our guide to COBRA open enrollment walks through the stay or switch decision.
What Happens If You Cancel and Miss Open Enrollment?
You wait for the next window, unless something in your life changes. For a plan you buy yourself in Texas, open enrollment runs from November 1, 2026 to January 15, 2027, as we explain in when does open enrollment end.
If you have already cancelled and the window has closed, you still have options. Read how to get health insurance outside of open enrollment and our guide to missed open enrollment.
Some routes stay open all year: a special enrollment period after a life event, Medicaid or CHIP if you qualify, and private plans that do not follow the open enrollment calendar.
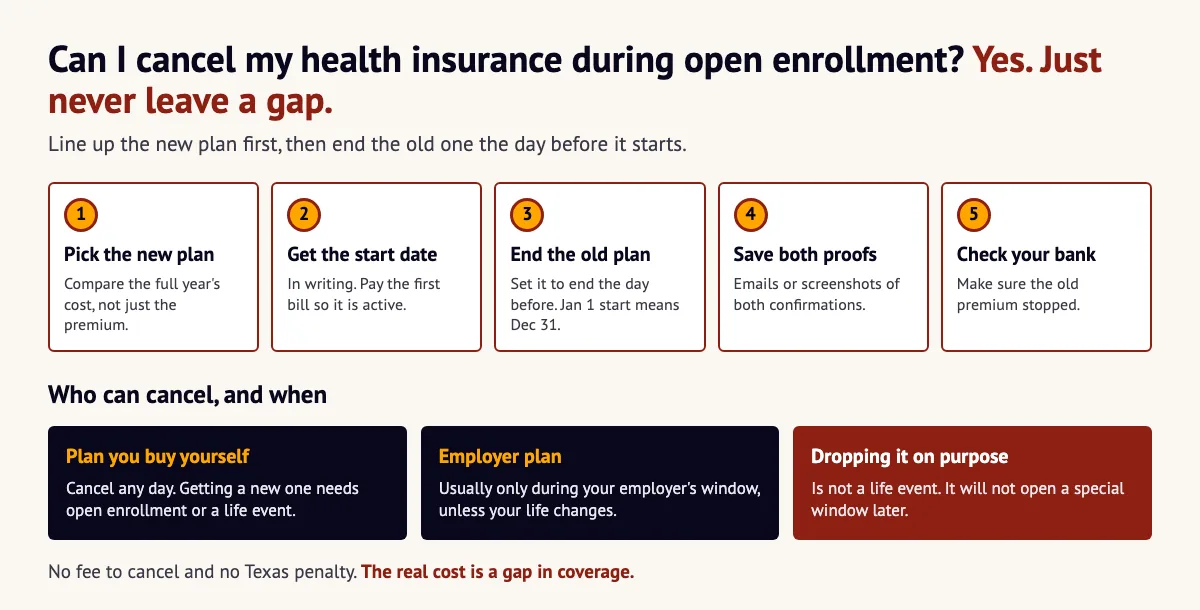
How Do You Cancel Without a Gap? A Five Step Checklist
Run these in order. Each step protects the one after it.
- Choose the new plan first. Compare the full year’s cost, not just the premium. Our guide on how to choose a health insurance plan in Texas shows how.
- Get the start date in writing. Pay the first premium so the plan is active.
- Cancel the old plan for the day before. Use your HealthCare.gov account, the carrier, or HR.
- Save both confirmations. Screenshots or emails are fine.
- Check your next bank statement. Make sure the old premium stopped.
Can I cancel my health insurance during open enrollment without any risk? If you follow these five steps, the risk is close to zero.
Does a Broker Help When You Cancel?
Not with the cancelling itself. Ending a plan is free and takes a few minutes, and you can do every step on this page yourself.
Where a broker helps is step one. A licensed Texas broker can price private PPO and association options next to the plans you already see, so you know what you are moving to before you end anything.
If you would like a second opinion, call (469) 361-4032 or ask for a free quote. There is no fee and no obligation.
Closing thoughts
Can I cancel my health insurance during open enrollment? Yes, and it is usually the best time to do it.
- Plans you buy yourself can be cancelled any day. Getting back in is the hard part.
- Employer plans usually open the exit only once a year. Open enrollment is that time.
- Dropping a plan on purpose is not a life event. Never cancel without the next plan lined up.
- Pick the end date yourself. The day before the new plan starts.
- Never just stop paying. Cancel cleanly and keep the confirmation.
For the full picture of this year’s window, start with our complete Texas open enrollment guide, or call (469) 361-4032 and we will help you line up the replacement first.