COBRA open enrollment is your yearly chance to change or leave the coverage you kept after a job ended. You can switch plan options inside your old employer’s plan, or drop COBRA for a private individual plan with no gap.
Most people on COBRA never use this window. They just keep paying the full premium. This guide explains both open enrollments, what each one lets you do, and how a broker can help you spend less.
What Is COBRA Open Enrollment?
The phrase covers two different windows. Many people mix them up, and that is where costly mistakes start.
- Your old employer’s open enrollment. This is the same window active workers get each year. The date is set by the employer’s plan year, often in the fall.
- Open enrollment for individual health insurance. It runs November 1 to January 15 for plans you buy yourself. Texas follows these federal dates.
The first window lets you change options within COBRA. The second lets you leave COBRA completely for a plan you own.
Ask your old employer’s benefits team for their exact dates in writing. They are often different from the individual market dates.
What Can You Change During Your Employer’s COBRA Open Enrollment?
The same choices active workers get. The U.S. Department of Labor says COBRA must match what similar active employees receive, including the right to choose among plan options during open enrollment.
In practice, that usually means you can:
- Move to a cheaper plan option, such as a high deductible plan instead of a PPO.
- Add family members on the same terms active workers can.
- Drop people from coverage, like a spouse who now has a job with benefits.
- Change dental or vision elections if the plan offers them.
One thing COBRA open enrollment cannot change is the price formula. You still pay the full premium plus up to a 2% fee.
How Much Does COBRA Cost After Open Enrollment?
Usually more than last year. COBRA premiums are tied to the employer’s plan, so when the plan renews at a higher rate, your COBRA bill goes up too.
The average work plan cost $9,325 a year for one person and $26,993 for a family in 2025, according to KFF. At 102%, that is about $790 a month for one person and about $2,290 a month for a family on COBRA.
Your numbers will differ. Read the renewal letter closely, because it shows the new monthly price before you decide anything.
Most plans also start a new deductible at renewal. If your plan year starts January 1, the deductible you already paid resets anyway. That removes one of the biggest reasons to stay on COBRA.
Can You Drop COBRA During Open Enrollment?
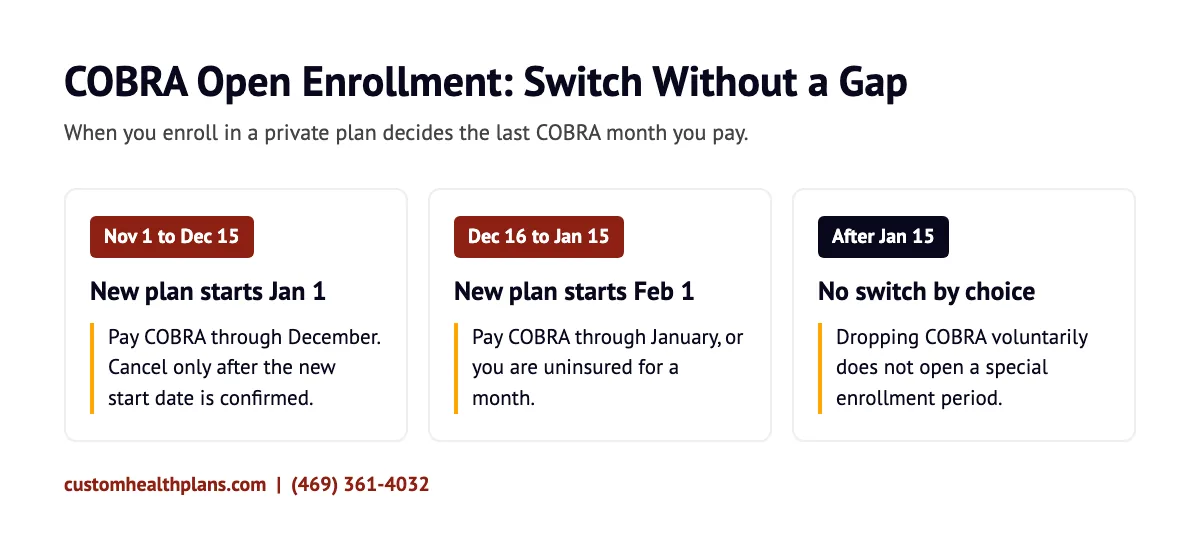
Yes. From November 1 to January 15, you can leave COBRA and buy an individual plan for any reason, says HealthCare.gov.
Outside that window, the rules are strict. Dropping COBRA by choice does not open a special enrollment period. You would wait until the next open enrollment, with no coverage in between.
A few events do let you switch mid-year:
- Your COBRA runs out, usually after 18 months.
- Your former employer stops paying part of the premium.
- Another life event, such as marriage, a baby or a move. See the full list of qualifying life events.
So if COBRA feels too expensive, open enrollment is usually the safest time to make the move.
COBRA vs a Private Plan: How Do They Compare?
Here is how staying on COBRA compares with switching to a private individual plan during open enrollment.
| Question | Stay on COBRA | Switch to a private plan |
| Who pays the premium? | You pay 100%, plus up to 2% | You pay the carrier’s rate |
| How long can you keep it? | Usually 18 months, then it ends | Renews every year |
| Same doctors? | Yes, same network | Depends on the plan you pick |
| Pre-existing conditions covered? | Yes | Yes, on major medical plans |
| Plan type choices | Only what your old employer offers | PPO, HMO, EPO, POS and HSA-qualified plans |
| Deductible | Resets at the employer’s plan year | Starts fresh in January |
Neither choice wins for everyone. A private plan often costs less for healthy people. COBRA often wins for people in active treatment with doctors they cannot replace.
Should You Stay on COBRA or Switch?
Your situation matters more than the premium alone. These four common cases show how the choice usually plays out.
You are healthy and see a doctor once or twice a year. A private plan usually costs less. You trade COBRA’s familiar network for a lower bill, and many PPO networks still include the same doctors.
You are in the middle of treatment. Staying is often the safer choice. Switching can mean new prior approvals, a new network and a fresh deductible while your care is ongoing.
Your family is on COBRA, but one person has new coverage. Drop that person at open enrollment. Each name you remove lowers the bill, and the rest of the family keeps their coverage.
Your COBRA ends within a few months. Plan the next step now. Running out of COBRA opens a special enrollment period, but open enrollment may let you move sooner, on a start date you choose.
If you are not sure which group you fit, a broker can model both paths with your real numbers. That usually takes one short phone call.
For a deeper look at the other routes, read our guide to COBRA alternatives in Texas.
How Can a Health Insurance Broker Help With COBRA Open Enrollment?
A broker turns COBRA open enrollment from a guess into a side-by-side decision. Here is what that looks like in practice.
1. We price your COBRA renewal against real private plans. You send us the renewal letter. We compare it with PPO, HMO and HSA-qualified plans from top carriers for the same people and the same start date.
2. We check your doctors and prescriptions first. A cheaper plan is no bargain if your doctor is out of network. We check each provider directory and drug list before you enroll.
3. We time the switch so there is no gap. Enroll by December 15 and a new plan usually starts January 1. Enroll after that and it starts February 1. We tell you exactly which COBRA month to pay last.
4. We run the deductible math. If you are deep into treatment, staying may be cheaper. We show you the full-year cost both ways, not just the monthly premium.
5. We check your family’s options one by one. Sometimes the best answer is a split, such as a spouse joining their new job’s plan while you move to a private plan.
Our help costs you nothing. Carriers pay brokers, and the premium is the same whether you use us or buy direct.
What Should You Do Before COBRA Open Enrollment Ends?
Work through this list in order. It keeps you from paying for coverage twice, or going without coverage at all.
- Find both deadlines. Write down your employer’s open enrollment dates and the individual market dates. Our post on when open enrollment starts and ends has the full calendar.
- Read your COBRA renewal letter. Note the new premium and any plan changes.
- List your doctors and prescriptions. These decide which plans are realistic.
- Get private quotes for the same start date. Compare total yearly cost, not just the premium.
- Enroll in the new plan before you cancel COBRA. Cancel only after you have the new plan’s start date confirmed.
- Keep paying COBRA until the new plan starts. You get at least a 30-day grace period for each payment, but do not count on it.
What Mistakes Do People Make During COBRA Open Enrollment?
The expensive mistakes are almost always about timing. Watch for these:
- Canceling COBRA too early. If the new plan starts February 1, you need COBRA through January.
- Dropping COBRA after January 15. Leaving by choice outside open enrollment means no special enrollment period.
- Confusing the two open enrollments. Your employer’s window may close weeks before November 1.
- Ignoring the renewal letter. Premiums often rise at renewal, and the change hits automatically.
- Forgetting your HSA. The IRS lets you pay COBRA premiums from an HSA tax-free.
Want to know what happens if a deadline slips? Read missed open enrollment for health insurance.
Is COBRA Open Enrollment Different in Texas?
The federal COBRA rules apply the same way in Texas. Texas also has its own continuation law for people COBRA does not cover.
The Texas Department of Insurance says workers not eligible for COBRA can keep a fully insured plan for up to nine months. People who had COBRA can add six more months after it ends.
Texas uses the federal dates for individual open enrollment. For the bigger picture, see our complete Texas open enrollment guide.
Still between jobs and not on COBRA yet? Start with health insurance between jobs in Texas.
Get a Free COBRA Comparison
Do not let COBRA open enrollment pass by default. Custom Health Plans compares your COBRA renewal with PPO and private plans from top carriers, then times the switch so you never have a gap.
Call (469) 361-4032 or Get a Free Quote.